However, commercial banks continue to dominate the market, acting as both the largest issuers and major investors, raising questions about the market's ability to diversify the economy's funding sources.
Growing pressure for long-term funding
Data from the Vietnam Corporate Bond Market Association show that corporate bond issuance totaled more than VND479.1 trillion (US$18.2 billion) in the first 10 months of 2026. Banks accounted for approximately 55 percent of the total, while real estate companies represented about 37 percent.
Mr. Pham Phu Khoi, the association's Secretary-General, highlighted a structural imbalance in the market: banks mobilize savings from households and businesses, issue corporate bonds to raise additional funds, and then become major investors in those same bonds.
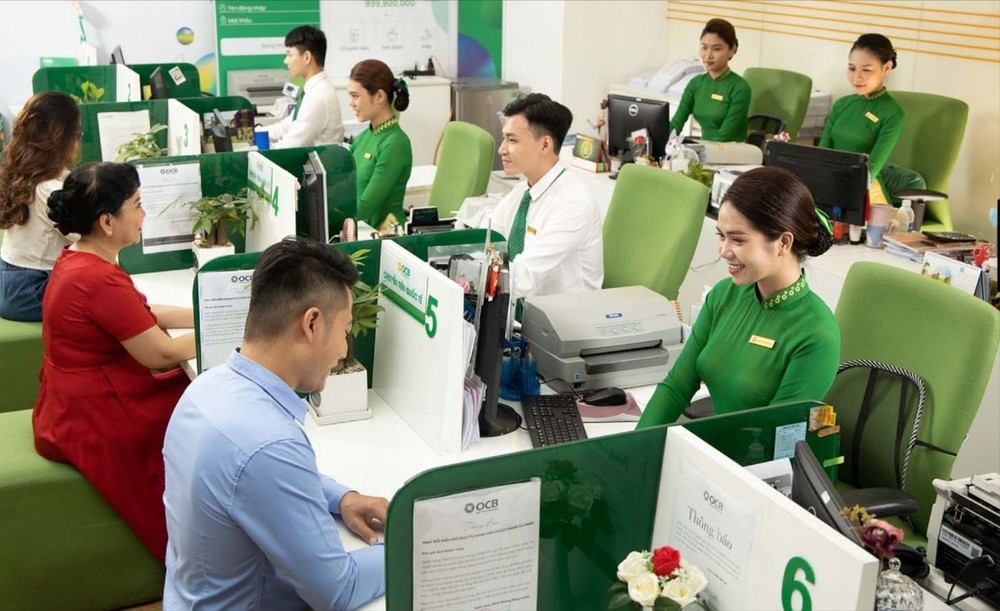
In October alone, newly issued corporate bonds totaled approximately VND31 trillion, according to Vietnam Investors Service (VIS Rating). Banks accounted for as much as 83 percent of issuance, compared with 6 percent for residential real estate companies and 11 percent for other sectors.
Despite a moderation in deposit rates, corporate bond yields remained relatively high, averaging 8.7 percent annually for banks and 12.5 percent for real estate issuers.
Mr. Nguyen Hung, CEO of Tien Phong Commercial Joint Stock Bank (TPBank), attributed banks' increased bond issuance to the mismatch between the maturity of deposits and their lending requirements. Although longer-term deposits typically carry interest rates about two percentage points higher per year, most savings deposits are short-term.
At the same time, the State Bank of Vietnam has tightened regulations governing the use of short-term funding for medium- and long-term lending. Banks must therefore raise additional capital through domestic and international bond markets to balance their funding structures and comply with prudential ratios.
This situation highlights the economy's continued heavy reliance on banks for capital. Commercial lenders are not only the largest providers of credit but also the leading corporate bond issuers and major investors in both corporate and government bonds. As a result, the corporate bond market has yet to establish itself as a genuinely broad-based funding channel for businesses.
The concentration is also evident in foreign funding. Mr. Nguyen Huu Hieu, CEO of FiinGroup Vietnam, said banks hold nearly 60 percent of the total volume of corporate bonds issued.
Banks also account for approximately 70 percent of foreign-currency funding raised from overseas, while non-bank businesses represent less than 30 percent. With multiple funding channels concentrated in the banking sector, the economy's ability to mobilize capital remains closely tied to banks' fundraising capacity and regulatory constraints.
Building institutions to strengthen the market
Vietnam's credit-to-GDP ratio has exceeded 140 percent, making its reliance on bank financing an increasingly significant concern for liquidity management and maturity risk. Developing capital markets and diversifying funding channels have therefore become urgent priorities.
Dr. Nguyen Tu Anh, Director of Macroeconomic Policy Research at VinUniversity, said the economy needs to expand medium- and long-term funding channels, with the corporate bond market playing a central role.
If businesses can raise long-term capital directly from investors, banks will be better positioned to focus on short-term financing and working capital needs. This would ease maturity and liquidity pressures on lenders and help stabilize interest rates.
Citing the Asian financial crisis in 1997 and the US financial crisis in 2008, Mr. Nguyen Tu Anh emphasized that bond markets can provide an important alternative source of financing when banking systems come under stress.
However, making corporate bonds a viable complement to bank lending requires more than simply expanding market size. Improving market quality and operational capacity is equally important.
Mr. Nguyen Huu Hieu noted that most outstanding corporate bonds currently carry floating interest rates, while pricing mechanisms and secondary-market trading remain underdeveloped. These weaknesses make the market more vulnerable to volatility and hinder the development of stable, long-term funding sources.
He called for stronger credit rating agencies, auditing firms, financial advisers and market intermediaries to improve transparency and narrow information gaps between issuers and investors.
Research by the Bank for Investment and Development of Vietnam (BIDV) estimates that total investment demand will reach US$280 billion to US$300 billion annually in 2026-2030, requiring average annual growth of 13-15 percent.
Dr. Can Van Luc, BIDV's chief economist, said the current funding structure was significantly imbalanced. From 2020 through September 2026, commercial banks supplied more than 50 percent of the economy's total funding, while capital markets, including equities and corporate bonds, contributed only around 14-15 percent.